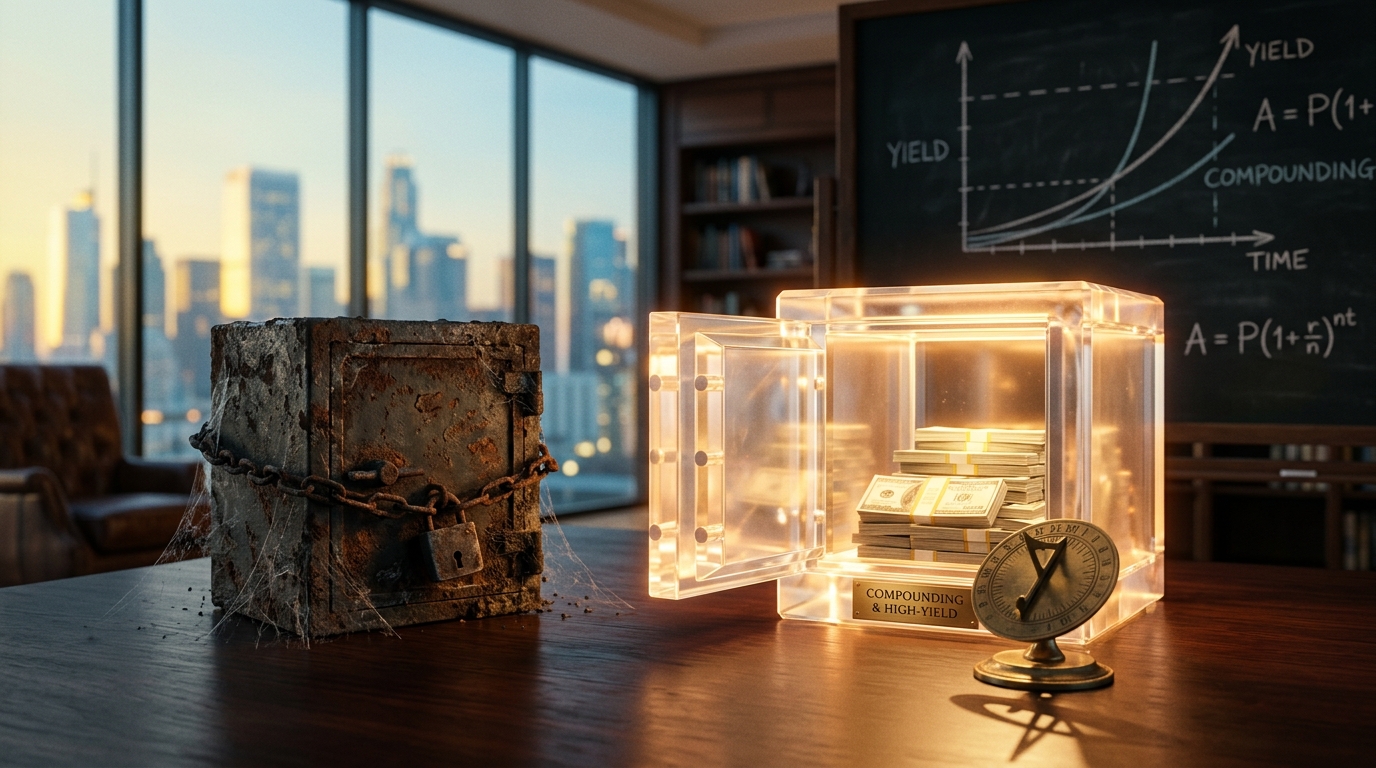
Leaving $25,000 inside a legacy 0.01% brick-and-mortar savings account with a $12 monthly maintenance charge yields -$141.50 in Year 1 before inflation even starts—while a fee-free High-Yield Savings Account (HYSA) at 4.25% generates +$1,062.50 risk-free. Yet millions of conscientious earners surrender over $1,000 a year to institutional inertia while legacy banks lend those exact deposits out at 8%+.
At Explore the Cosmos, unforced systemic friction is unacceptable—whether tuning aerodynamic drag or auditing ledgers offline with FinFortress. Your emergency reserve must stay liquid, fee-free, and directly insured. Here is how High-Yield Savings Accounts work, the real 20-year after-tax math, and how to separate direct chartered banks from fragile fintech wrappers.
What It Is: The Mechanics of High-Yield Savings Accounts
At its core, a High-Yield Savings Account (HYSA) is structurally identical to any conventional savings vehicle: it is a deposit account where your principal remains completely liquid, accessible on demand, and backed by government insurance (such as the Federal Deposit Insurance Corporation, or FDIC, in the United States, typically up to $250,000 per depositor, per insured institution).
The defining divergence lies in the Annual Percentage Yield (APY). While traditional mega-banks offer rates hovering between 0.01% and 0.35%, an HYSA pays a competitive yield—consistently tracking benchmark central bank interest rates. Why can online high-yield institutions afford to pay ten to forty times more interest than legacy branch banks? The answer is not financial magic; it is structural overhead:
- Zero Branch Real Estate: Digital institutions do not lease prime commercial real estate on downtown city corners, pay property taxes, or maintain fleets of physical bank branches.
- Streamlined Labor Costs: Operating digitally eliminates the massive operational payroll required to staff physical teller windows and branch management.
- Deposit Acquisition Efficiency: Instead of spending billions on stadium naming rights and promotional credit card mailers, high-yield institutions use attractive, transparent interest rates as their primary customer acquisition engine.
How It Works: The 2026 Rate Landscape and the Hidden Penalty of Inertia
Leaving your cash in a standard legacy account is not a neutral, safe decision; entering 2026, empirical banking data demonstrates that it is an active financial penalty:
1. The 2026 Interest Rate Divide
With benchmark central bank interest rates stabilizing in the 3.75% to 4.00% range, competitive digital HYSAs reliably deliver between 4.0% and 4.6% APY. In contrast, the national average savings rate across traditional brick-and-mortar banks remains languishing at roughly 0.35%, with the largest legacy institutions still paying a negligible 0.01%.
To grasp the true long-term magnitude of this disparity, model a $25,000 emergency reserve across 5, 10, and 20 years factoring in a 25% marginal ordinary income tax on interest, a conservative 3.0% annual inflation rate, and a typical $12/month legacy bank maintenance fee:
| Time Horizon | Legacy Bank (0.01% APY + $12/mo Fee) | Direct Chartered HYSA (4.25% APY / 3.19% Net) | Neo-Bank Promo (4.50% APY / 3.38% Net) |
|---|---|---|---|
| Year 1 | $24,858 nominal -$142 net cash bleed |
$25,797 after-tax +$939 ahead of legacy |
$25,844 after-tax +$47/yr vs. Direct HYSA |
| Year 5 | $24,292 nominal → $20,955 real -16.2% purchasing power |
$29,247 nominal → $25,228 real +$4,274 real preserved |
$29,513 nominal → $25,458 real +$230 real over Direct HYSA |
| Year 10 | $23,584 nominal → $17,549 real -29.8% purchasing power |
$34,215 nominal → $25,459 real +$7,910 real preserved |
$34,841 nominal → $25,925 real +$466 real over Direct HYSA |
| Year 20 | $22,167 nominal → $12,273 real (-50.9%) More than half of moat destroyed |
$46,825 nominal → $25,926 real +$13,653 real preserved |
$48,557 nominal → $26,885 real Only ~$48/yr extra real yield |
Look at the risk-adjusted engineering lesson: switching from a fee-charging legacy bank to a 4.25% Direct Chartered HYSA protects $13,653 in real purchasing power over 20 years. Conversely, chasing an extra 0.25% teaser rate at an unchartered fintech neo-bank adds barely $47/year after tax—hardly worth exposing $25,000 to third-party BaaS middleware freeze risk.
2. The Sneaky Resurgence of “Maintenance Fees”
Compounding the insult of negligible interest rates, legacy banks routinely extract $10 to $15 per month in arbitrary “monthly service charges” unless you maintain rigid minimum balances or route mandatory direct deposits through their pipeline. If an unforeseen circumstance causes your balance to dip below their threshold for forty-eight hours, you are penalized. In 2026, paying an institution a fee to hold your liquid capital is an obsolete, predatory artifact of 20th-century banking.
3. Direct Chartered Banks vs. “Neo-Bank” Intermediaries
As depositors seek higher yields, hundreds of flashy fintech startups and “neo-banks” have flooded the market. However, a vital structural distinction must be made: many neo-banks are not banks. They are marketing platforms and software wrappers that partner with third-party depository banks.
Many utilize “FDIC Cash Sweep” mechanisms, dispersing customer deposits across a syndicate of smaller partner banks to offer expanded multi-million-dollar FDIC coverage. While sweep programs are legitimate financial tools, fintech intermediaries often introduce operational friction: automated customer service handled exclusively by AI chatbots, withdrawal settlement delays during platform disruptions, and complex terms of service. For your non-negotiable emergency reserve, you want direct, unencumbered security.
Why It Matters: Comparing Banking Architectures
Choosing where to store your liquidity should never be guided by television commercials or catchy marketing slogans. Evaluate your banking relationships through rigorous operational parameters:
| Feature | Legacy Pillar Bank | Fintech “Neo-Bank” Wrapper | Direct Chartered HYSA (Our Preference) |
|---|---|---|---|
| Typical APY (2026) | 0.01% – 0.35% (Severe capital drag) | 3.80% – 4.75% (Competitive) | 4.00% – 4.50% (Consistently high) |
| Monthly Service Fees | $10 – $15 (Unless waived by conditions) | $0 (Free, but upsells premium tiers) | $0 (Zero conditions, zero fees) |
| Insurance Structure | Direct FDIC Insurance ($250k) | Pass-through / Sweep Network (Third-party) | Direct FDIC Insurance ($250k) |
| Customer Support | Physical branch / phone support | Automated AI chatbots / email tickets | Dedicated phone & secure digital support |
| Data Privacy | Extensive behavioral marketing & ads | Heavy tracking; data monetized via partners | Standard regulated privacy protections |
Real Examples: The Sovereign Cash Protocol
To optimize your emergency fund, parking your capital in a high-yield account is only half the battle. You must organize your accounts to prevent friction, emotional spending leaks, and privacy invasions.
1. Choose a Direct Chartered Institution
When selecting an HYSA, look for institutions with a direct national bank charter (such as Ally Bank, Marcus by Goldman Sachs, Discover Bank, or American Express National Bank) rather than a third-party fintech wrapper. Verify that the institution provides direct FDIC insurance, has zero monthly maintenance fees, requires no minimum initial deposit, and allows unlimited, friction-free ACH transfers.
2. The “Decoupled Fortress” Architecture
One of the most effective psychological tactics to conquer impulsive spending is geographic account separation. Never keep your high-yield emergency fund at the exact same financial institution where you hold your everyday checking account. When your emergency cushion is visible inside your daily mobile banking dashboard, your brain perceives it as available spending capital.
By holding your emergency fund at an external, dedicated high-yield institution, you introduce an intentional 24-to-48-hour transfer buffer. The money is 100% liquid and accessible during genuine crises, but safely insulated from late-night impulse purchases.
3. Maintain Local Telemetry with FinFortress
Many modern budgeting platforms attempt to bridge your bank accounts by demanding your login credentials and passwords through cloud-based data aggregators. Once connected, they track every interest deposit, monitor your liquidity, and use that telemetry to target you with loan advertisements. At Explore the Cosmos, we reject this invasion of privacy.
Instead, download your monthly statement directly from your HYSA as a clean CSV file and import it into our local-first desktop application, FinFortress. Running 100% offline, FinFortress parses your interest credits, verifies your emergency reserve coverage against your actual monthly expenses, and plots your progress on a local Wealth Waterfall chart. Your financial data stays on your machine, exactly where it belongs.
Trade-offs & Edge Cases: Rate Cuts, State Taxes, and Yield-Chasing Friction
HYSAs are superior to 0.01% legacy banks, yet they carry three structural limitations you must plan around:
| Edge Case / Risk | The Hidden Trade-off | The Engineering Mitigation |
|---|---|---|
| Variable Rate Compression | HYSA APYs are floating rates: when central banks cut benchmark rates by 2.0%, your 4.25% yield drops automatically within weeks. | Use HYSAs for 100% liquid operating reserves; if locking away cash for a known 12-month horizon (e.g., house down payment), lock yields via T-bills or no-penalty CDs. |
| State & Local Income Tax Drag | HYSA interest is fully taxable at both federal and state levels (costing 5%–13% extra in high-tax states like California or New York). | For cash reserves above $25,000 in high-tax jurisdictions, compare after-tax yield against direct 3-month Treasury bills (exempt from state and local income tax). |
| Teaser APY Chasing vs. Real Hourly Wage | Spending 4 hours moving accounts every quarter to chase a +0.20% promo rate (+$50/yr on $25,000, or ~$37.50 after tax). | You earn less than $10/hr handling redundant paperwork. Pick one reliable, directly chartered HYSA paying near top-decile rates and ignore tiny teaser spreads. |
Today’s 5-Minute Task: The Legacy Bank Extraction Audit
Take five minutes to stop paying legacy banks to hold your cash:
- Inspect Your Current APY & Fees: Open your savings account summary and find the exact current APY alongside any monthly service or minimum-balance penalty fees.
- Compute Annual Extraction Loss: Multiply your balance by
(0.0425 − Current APY)and add12 × Monthly Fee. On $15,000 at 0.01% with a $10 fee, you are losing $756/year. - Verify Direct Bank Charter: Before opening a replacement HYSA, confirm the institution holds its own FDIC Certificate Number on the FDIC BankFind directory (not a fintech middleware partner).
- Initiate the First ACH Transfer: Open the external HYSA with $0 monthly fees and move your emergency reserves out of your daily checking interface.
The Path Forward: Make Your Reserves Work for You
Your emergency fund is the bedrock of your financial fortress. It is the silent, unshakable foundation that empowers you to invest aggressively, take calculated career risks, and walk through life unburdened by financial anxiety.
Do not allow institutional inertia or legacy bank fee-gouging to dilute your hard-earned capital. Move your reserves to an established, fee-free high-yield account, demand competitive market yields, and manage your cashflow with sovereign, local-first precision. Real wealth begins with stopping the leaks.
Leave a Reply