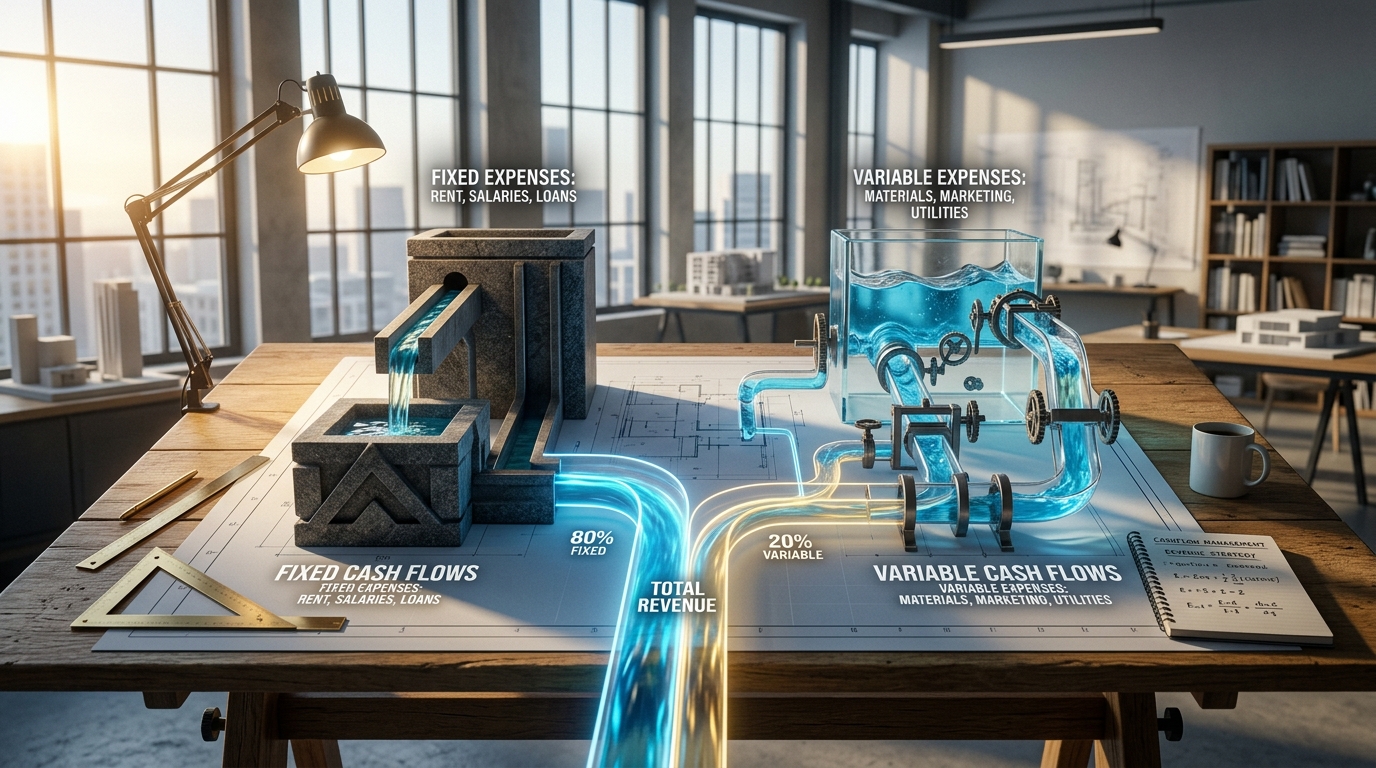
Tracking dozens of micro-budget categories fails because cognitive friction scales faster than financial clarity: you only need to engineer two structural variables—your Fixed Contractual Floor and your Dynamic Variable Flow. When fixed commitments consume 70%+ of your net paycheck, skipping $4 coffees cannot cure a structural cashflow deficit.
At Explore the Cosmos, we model personal cashflow using fluid dynamics: an engineer never predicts pipe pressure by tracking individual molecular collisions—they measure bulk volumetric flow and baseline pipe diameter. Separating non-negotiable fixed commitments from dynamic spending and converting irregular “lumpy” bills into monthly sinking funds eliminates budgeting willpower entirely.
What It Is: The Structural Anatomy of Cashflow
To master your money, you must categorize your outflows by their contractual rigidity rather than arbitrary emotional labels like “needs” versus “wants.” In first-principles accounting, every outgoing dollar falls into one of two physical categories:
1. Fixed Expenses (The Contractual Floor)
Fixed expenses are predictable, recurring commitments that occur at set frequencies and non-negotiable amounts. They are the non-negotiable overhead required to maintain your baseline existence in society. Once initiated, they do not adjust based on your daily behavior; you owe them regardless of whether you feel energetic, fall ill, or take unpaid leave.
Core fixed expenses represent your foundation—what we call the “Four Walls”:
- Shelter: Rent or mortgage principal and interest.
- Structural Utilities: Base electricity, heating, water, and broadband internet.
- Contractual Debt Service: Student loan minimums, vehicle financing, personal loan amortizations.
- Protection: Health insurance, term life insurance, renter’s or homeowner’s policies, and auto insurance.
- Committed SaaS & Subscriptions: Cloud storage, gym memberships, streaming services, and software toolchains.
2. Variable Expenses (The Dynamic Flow)
Variable expenses are flexible, behavior-dependent outlays that fluctuate in volume and timing based on daily choices, lifestyle preferences, and immediate needs. While some variable costs are vital for physical survival (such as groceries), the exact financial magnitude of the outflow remains directly under your real-time discretionary control.
Key variable streams include:
- Nutrition: Supermarket groceries, dining out, coffee shops, and meal deliveries.
- Mobility: Gasoline, public transit passes, rideshares, tolls, and parking fees.
- Personal Care & Apparel: Clothing, haircuts, toiletries, and fitness gear.
- Discretionary Leisure: Concert tickets, hobbies, travel, weekend entertainment, and tech hardware upgrades.
How It Works: The 2026 Structural Squeeze and “Hidden Fixed Costs”
Managing cashflow has become significantly more complex in recent years. Entering 2026, consumer economic data highlights three structural trends that have warped the boundary between fixed and variable spending, trapping millions of earners in chronic cashflow deficits:
1. The Expansion of Structural Fixed Overhead
In 2026, fixed commitments consume a historic high of household income. Median housing costs frequently command 35% to 45% of net take-home pay in major metropolitan hubs. Concurrently, auto and homeowner insurance premiums have experienced multi-year surges, driven by severe weather risks, higher construction repair indices, and the sophisticated sensor arrays in modern vehicles. When fixed overhead locks up 65% to 75% of your net income before you even purchase a loaf of bread, your financial margin of error shrinks to zero.
2. The Subscription Economy and “Micro-Fixed Bleed”
A decade ago, entertainment and software were purely variable purchases: you bought a movie ticket or purchased software on a disk once. In 2026, nearly every consumer product has morphed into a recurring subscription. The average household now bleeds between $500 and $600 annually across fragmented digital micro-services—streaming platforms, cloud storage, fitness apps, and delivery memberships. Because each line item appears negligible ($9.99, $14.99), they evade scrutiny. In reality, they act as permanent fixed anchors dragging down your monthly baseline.
3. The Trap of “Lumpy” Irregular Expenses
The most common cause of financial instability is confusing irregular fixed obligations with unexpected emergencies. Costs like annual auto registration, quarterly municipal water bills, semi-annual car insurance premiums, and routine dental cleanings are not surprise emergencies; they are 100% predictable events that simply occur on non-monthly cycles. When households fail to model these as recurring monthly liabilities, these “lumpy” expenses hit checking accounts like torpedoes, instantly detonating monthly budgets.
Why It Matters: Comparing Rigid Budgets to Hydraulic Flow Mapping
Traditional personal finance treats budgeting as an act of moral deprivation. We reject that framing entirely. Cashflow management is simply a hydraulic engineering problem: balancing inflow pressure against baseline pipe resistance and fluid output.
Worked Calculation: The 72% vs. 48% Fixed Floor (Exact 5-, 10-, and 20-Year Wealth Divergence)
To observe why cutting daily variable treats fails when structural overhead is oversized, compare two households earning an identical $5,500/month net take-home pay ($66,000/year) and facing $2,400/year ($200/month) in predictable irregular obligations (insurance, auto registration, renewals, gifts). Both spend the exact same $1,200/month on variable groceries, fuel, and dining—yet diverge sharply in fixed-cost engineering (compounded at 7.0% real net return after inflation and 0.20% ETF TER):
| Cashflow Line / Horizon | Household A: Over-Leveraged (72% Fixed Floor) | Household B: Engineered Baseline (48% Fixed + Sinking Fund) |
|---|---|---|
| Fixed Contractual Floor (Housing, utilities, car/debt, SaaS) |
$3,960 / mo (72.0%) ($2,350 housing, $580 auto loan, $420 utils, $390 ins/debt, $220 SaaS) |
$2,640 / mo (48.0%) ($1,650 housing, $0 car loan, $320 utils, $610 ins/other, $60 lean SaaS) |
| Lumpy / Sinking Fund Handling | $0 pre-funded; $2,400 annual bills trigger 22% APR card debt (~$240/mo effective drag) | $200 / mo automated Sinking Fund (4.0% HYSA; $0 credit card interest ever paid) |
| Variable Discretionary Spend | $1,200 / mo (21.8%) | $1,200 / mo (21.8% — identical daily lifestyle) |
| Monthly Investable Surplus | $100 / mo (1.8% savings rate) | $1,460 / mo (26.5% savings rate) |
| 5-Year Compounded Wealth | $7,159 | $104,526 (+$97,367 ahead) |
| 10-Year Compounded Wealth | $17,308 | $252,704 (+$235,396 ahead) |
| 20-Year Compounded Wealth | $52,093 | $760,553 (+$708,460 net wealth delta) |
Notice the mechanical lesson: Household B does not drink fewer coffees or restrict groceries—both spend $1,200/month on daily life. By shrinking the Fixed Contractual Floor from 72% to 48% and pre-funding $200/month into a sinking fund, Household B generates 14.6× higher monthly wealth and accumulates $708,460 more capital over 20 years on the exact same paycheck.
| Dimension | The Legacy Micro-Budgeting Model | The First-Principles Flow Model (Our Approach) |
|---|---|---|
| Core Method | Manually logging dozens of micro-categories in arbitrary spreadsheets. | High-level structural mapping: Fixed Floor vs. Dynamic Variable Streams. |
| Handling Irregular Costs | Ignored until they strike; paid via credit cards or emergency funds. | Converted into monthly Sinking Funds (annual cost divided by 12). |
| Tool Architecture | Third-party cloud apps scraping bank credentials and selling ads. | 100% offline, local-compute desktop tools (like FinFortress) that map CSVs locally. |
| Cognitive Overhead | Extreme friction; requires daily receipt recording and mental willpower. | Zero daily friction; automated fixed transfers, flexible weekly variable buckets. |
| Adaptability | Rigid; breaks when a single category overspends, causing guilt and burnout. | Uses “Flex Bands” (elastic buffers) to absorb seasonal shifts naturally. |
Real Examples: How to Map and Automate Your Flow
To eliminate financial complexity, you do not need complicated financial software or cloud accounts that harvest your personal data. Follow this three-step blueprint to establish complete cashflow visibility:
1. Run a 90-Day Local Data Extraction
Download the last three months of bank and credit card statements in raw CSV format. Do not upload these files to cloud-based aggregators that scrape your banking telemetry and monetize your spending patterns. Instead, utilize private, local-first tools like FinFortress.
Our desktop application processes your financial files directly on your machine using an offline machine learning classifier (LinearSVC). It automatically sorts transactions into structural fixed commitments and dynamic variable outlays, rendering an interactive Sankey cashflow diagram. In a single visual sweep, you can watch your net paycheck enter on the left and see precisely what percentage flows into your fixed bedrock versus your variable discretionary currents.
2. Transform “Lumpy” Costs into Monthly Sinking Funds
Identify every irregular expense that strikes once or twice a year:
- Car Insurance ($1,200/year) = $100 / month
- Amazon Prime & Software Renewals ($360/year) = $30 / month
- Annual Veterinary Exam ($240/year) = $20 / month
- Holiday & Birthday Gifting ($600/year) = $50 / month
Sum these figures ($200 per month in this example) and automate a recurring transfer into a dedicated high-yield “Sinking Fund” account the day your paycheck arrives. When the annual insurance invoice lands in your mailbox, the capital is already waiting. You eliminate the emotional shock entirely.
3. Implement the Two-Account Decoupling Architecture
Eliminate daily budgeting willpower by physically separating your fixed baseline from your variable spending:
- Account A (The Fixed Fortress): Your paycheck deposits here. All fixed bills (rent, utilities, debt minimums, insurance, subscriptions, and sinking fund transfers) are automated directly from this checking account. You never carry a debit card linked to this account.
- Account B (The Dynamic Spender): Calculate your remaining variable surplus after funding your fixed obligations and your non-negotiable savings/debt payoff targets. Transfer this discretionary allowance to a separate spending account once a week or twice a month. You are free to spend every cent in this account without guilt, tracking, or spreadsheets. When it reaches zero, spending pauses until the next scheduled transfer.
Trade-offs & Edge Cases: Where Simple Two-Bucket Systems Need Calibration
Even a streamlined hydraulic cashflow model exhibits friction if implemented blindly without accounting for three structural edge cases:
| Edge Case / Scenario | The Failure Mode | The Engineering Correction |
|---|---|---|
| Essential Variable Floor (Food & Fuel) | Putting groceries and transit fuel into Account B and accidentally draining it on concert tickets by the 10th of the month. | Anchor a non-negotiable baseline food/fuel floor inside Account A—or restrict Account B transfers to a weekly cadence (every Friday) so you can never blow a month’s food budget in one weekend. |
| Sinking Fund Over-Fragmentation | Opening 12 separate bank sub-accounts for vet bills, gifts, tires, and taxes—recreating spreadsheet complexity and leaving excessive idle cash earning minimal yield. | Consolidate every predictable non-monthly cost into one single pooled Annual Buffer HYSA (earning ~3.5%–4.0% APY) funded by one monthly transfer. |
| Volatile / Freelance Income | Automating rigid Account B transfers when monthly commissions or invoices swing ±40%. | Calibrate Account A’s Fixed Floor strictly to your lowest trailing 90-day income month; hold excess windfalls in a cash smoothing reservoir before releasing discretionary transfers. |
Today’s 5-Minute Task: Compute Your Fixed-Overhead Ratio
Take five minutes to verify your structural rigidity and pre-fund your biggest annual surprise:
- Sum Monthly Fixed Commitments: Add rent/mortgage, base utilities, insurance, minimum loan payments, and all recurring subscriptions (or read the Fixed Stream directly from your local FinFortress Sankey output).
- Calculate Your Fixed Ratio: Divide your total fixed sum by your monthly net take-home pay:
Fixed Ratio = Fixed Commitments ÷ Monthly Net Pay. Aim to compress this below 50%–55% over time. - Identify Top 3 Lumpy Bills: List your three largest annual or semi-annual expenses (e.g., car insurance, annual registrations, holiday travel) and divide their combined annual cost by 12.
- Automate One Sinking Transfer: Schedule a monthly transfer of that exact 1/12th figure into a separate High-Yield Savings Account on payday so your next annual bill is neutralized in advance.
The Path Forward: Simplicity as Ultimate Sophistication
Mastering your cashflow is not about restricting your joy; it is about eliminating unconscious waste so you can fund what genuinely matters. When your fixed expenses are lean, protected, and fully automated, and your irregular obligations are pre-funded through sinking funds, financial anxiety evaporates.
By stepping away from tedious manual micro-tracking and embracing high-level structural mapping, you gain complete command over your resources. You protect your privacy, conquer debt, and create a calm, sustainable foundation for lifelong financial sovereignty.
Leave a Reply