A $25,000 gross raise does not make you wealthier if your fixed monthly burn expands by $1,400 the day your new paycheck clears. Every permanent lifestyle upgrade levies a double mathematical penalty: it destroys the surplus capital you could have compounded, while simultaneously inflating the portfolio size required for financial independence.
At Explore the Cosmos, we analyze personal finance through orbital mechanics and first-principles math: adding more thrust to a rocket achieves zero net acceleration if structural mass expands at the exact same rate. Boosting top-line compensation fails to buy freedom if your spending floor balloons alongside it. This dynamic is lifestyle inflation—and it is the primary mechanical leak separating high earners from true financial autonomy.
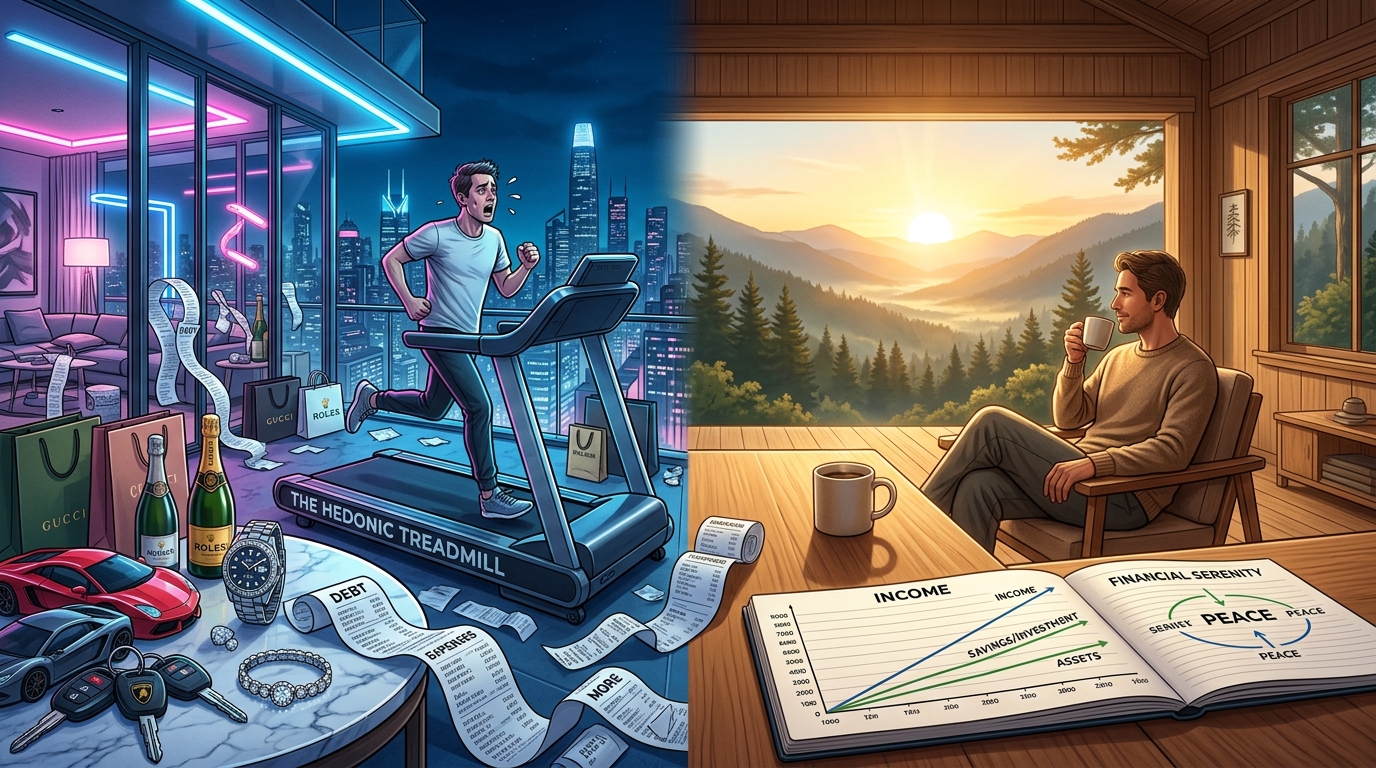
What It Is: The Hedonic Treadmill and the Elastic Baseline
In evolutionary psychology, human satisfaction is governed by what behavioral scientists call hedonic adaptation. When humans experience an upgrade in environmental conditions—whether a softer bed, a faster vehicle, or an apartment with panoramic floor-to-ceiling windows—the brain releases a brief burst of dopamine. For a fleeting window of days or weeks, the new acquisition produces genuine pleasure.
However, the human nervous system is an adaptive prediction machine designed for survival, not eternal euphoria. In short order, neurochemical novelty dissipates and the extraordinary luxury becomes your new mandatory floor:
- Baseline Reset: Yesterday’s indulgence transforms into today’s baseline expectation.
- Diminishing Returns: To trigger the same subjective reward signal, you are compelled to upgrade consumption again.
- Zero Net Progress: You expend massive energy earning more, yet remain stranded at the exact same emotional setpoint.
How It Works: The 2026 Data on the High-Earner Trap
Lifestyle inflation is not a minor financial inconvenience; entering 2026, empirical consumer data reveals that it has become an acute systemic crisis among middle-class and professional households:
1. The 36% Shock: Six-Figure Paycheck-to-Paycheck Living
Recent economic reports in 2026 confirm that an astonishing 36% of consumers earning more than $250,000 annually report living paycheck to paycheck. When an earner commanding a top-percentile wage struggles to absorb a $3,000 emergency expense without swiping a high-interest credit card, the issue is visibly not income scarcity. It is fixed-cost rigidity: oversized mortgages, multi-year luxury vehicle financing, private tuitions, and recurring lifestyle maintenance.
2. The “HENRY” Dilemma: Looking Rich vs. Being Wealthy
Modern professionals frequently find themselves categorized as HENRYs (High Earners, Not Rich Yet). Algorithmic social feeds create what researchers term “abundance denial”—tricking high earners into feeling impoverished unless they display leased luxury cars and five-star travel. They convert high-taxed wages directly into depreciating status goods, leaving their balance sheets brittle against any economic shock.
3. The Compounding Trap of Structural Fixed Costs
Lifestyle inflation rarely strikes through occasional small indulgences; it takes hold through cascading structural upgrades. Upgrading from a $1,800 apartment to a $3,500 luxury loft triggers simultaneous cost multipliers across your entire cashflow architecture:
- Direct Overhead Expansion: Utility bills, renter’s insurance, and local municipal costs scale proportionately with square footage.
- Neighborhood Price Drift: Surrounding grocers, gyms, and dining venues frequently charge a 25%–30% geographic markup.
- Complementary Furnishings: Larger floorplans generate immediate peer pressure to spend thousands on new furniture and decor.
Why It Matters: Cashflow Dynamics and the True Cost of Upgrades
Every dollar permanently annexed by lifestyle creep levies a double penalty on your future freedom. First, that dollar disappears from your compounding investment engine. Second, raising your annual living expense increases the portfolio size required to fund Financial Independence (FIRE) under the 4% rule (25× annual spending).
Worked Calculation: The Double Penalty of Spending a $25,000 Gross Raise
Consider an earner making $75,000 gross ($4,500/month net take-home) who spends $3,500/month ($42,000/year) and invests $1,000/month (a 22.2% savings rate). Their baseline 25× FIRE target is $1,050,000.
Now suppose they negotiate a +$25,000 gross raise (to $100,000). After a realistic ~32% marginal income and payroll tax rate, actual net take-home increases by +$17,000/year (+$1,417/month)—bringing total net income to $5,917/month. Here is the exact 5-, 10-, and 20-year divergence assuming a 7.0% real net annualized return (after inflation and a 0.20% index ETF TER):
| Metric / Horizon | Path A: 100% Lifestyle Creep (Spend entire +$1,417/mo raise) |
Path B: The 80/20 Raise Split (Invest +$1,134/mo, Enjoy +$283/mo) |
|---|---|---|
| New Monthly Spending | $4,917 / month ($59,004 / year) | $3,783 / month ($45,396 / year) |
| Monthly Investment | $1,000 / month | $2,134 / month |
| Effective Savings Rate | 16.9% (dropped despite the raise) | 36.1% |
| Required 25× FIRE Portfolio | $1,475,100 (+$425,100 penalty) | $1,134,900 (+$84,900 increase) |
| 5-Year Invested Wealth | $71,593 | $152,779 (+$81,186 ahead) |
| 10-Year Invested Wealth | $173,085 | $369,363 (+$196,278 ahead) |
| 20-Year Invested Wealth | $520,927 (35.3% of goal) | $1,111,657 (98.0% of goal — +$590,730 ahead) |
| Time to Full Financial Independence (from $0) | 32.4 years | 20.2 years (12.2 years of life reclaimed) |
The math is unforgiving: absorbing the entire $1,417 monthly net raise into fixed lifestyle upgrades increases your required retirement portfolio by $425,100 while starving your investments. Deploying the 80/20 Raise Split still grants a permanent $283/month quality-of-life upgrade, yet generates $590,730 more real wealth over 20 years and buys back 12.2 years of working life.
| Metric | The Inflated Lifestyle Model | The Deliberate Baseline Model (Our Approach) |
|---|---|---|
| Handling a Raise | Immediately upgrade apartment, lease a newer car, subscribe to new services. | Pre-allocate 80% of net raise directly to debt elimination and assets before it hits checking. |
| Asset vs. Liability Focus | Prioritizes visible, depreciating liabilities that signal status (cars, fashion). | Prioritizes invisible, cashflow-generating assets that create sovereignty (equities, cash reserves). |
| Expense Architecture | Heavy, rigid fixed costs; difficult to downsize during downturns. | Light, flexible fixed costs; wide discretionary buffer that absorbs shocks easily. |
| FIRE Target Multiple | Requires $3M+ portfolio just to fund lifestyle upkeep (25x of $120k/yr burn). | Requires $1.25M portfolio for identical comfort (25x of $50k/yr intentional burn). |
| Visibility & Tracking | Ignored or delegated to cloud apps that sell ads and push new credit lines. | Visualized locally via offline cashflow tools (like FinFortress) with zero data leakage. |
Real Examples: How to Break the Hedonic Loop and Keep Your Gains
Avoiding lifestyle inflation does not require embracing ascetic deprivation or wearing threadbare clothes. It requires establishing clear mathematical boundaries and automating intentional friction before lifestyle creep takes root.
1. Deploy the “80/20 Raise Split” Protocol
When you receive a salary increase or windfall bonus, treat the new capital with strict pre-commitment. Commit to splitting the net surplus into two distinct pools:
- The 80% Sovereign Buffer: Immediately redirect 80% of the net monthly increase toward high-interest debt eradication, building your liquid emergency reserve, or funding index investments. Because you never lived on this money, you will never psychologically miss it.
- The 20% Celebration Pool: Take the remaining 20% and allocate it guilt-free toward discretionary lifestyle upgrades—a dinner at a memorable restaurant, higher quality running shoes, or a weekend getaway. This acknowledges your hard work without mortgaging your future.
2. Audit Structural Overhead with Local Cashflow Mapping
Many earners do not realize they have succumbed to lifestyle inflation because cloud-based budgeting tools obscure the big picture. When apps hide behind recurring SaaS fees, cloud synchronization delays, and fragmented category tags, you lose high-level strategic awareness.
This is why we rely on FinFortress, our privacy-first desktop application. By running 100% offline and utilizing a local LinearSVC text classifier to analyze bank CSV statements directly on your hard drive, FinFortress generates instantaneous Sankey cashflow diagrams and Wealth Waterfall charts. Seeing your income split into a visual delta reveals lifestyle creep instantly: you can literally watch your “Discretionary Stream” widen over three consecutive quarters and pinpoint the exact subscriptions, dining patterns, and retail habits siphoning off your salary increase.
3. Institute the “30-Day Delay Rule” for Capital Upgrades
When you feel the sudden urge to upgrade an asset—such as buying the latest smartphone, trading in a reliable vehicle, or buying expensive home audio gear—impose a mandatory 30-day cooling-off window. Document the desired item, its price in working hours, and the date in a private plain-text file. If, after thirty full days, the purchase still promises profound, repeatable utility rather than fleeting hedonic novelty, proceed intentionally. In over 70% of instances, the impulse will evaporate completely.
Trade-offs & Edge Cases: When Raising Expenses Makes Mathematical Sense
Applying anti-inflation rules rigidly without examining underlying cashflow utility creates false economies. Evaluate potential spending increases against these three edge cases:
| Edge Case / Scenario | The Trap | The Rational Rule |
|---|---|---|
| Time-Buying & Commute Compression | Treating higher rent near work as pure “lifestyle creep.” | If paying +$300/mo in rent eliminates a 60-minute daily commute, you reclaim ~21.5 life-hours/month while cutting vehicle depreciation—often raising your net Real Hourly Wage. |
| Health & Ergonomic Longevity | Under-investing in whole foods, sleep ergonomics, or preventative care to force an artificial 60% savings rate. | High-ROI health expenditures protect your future cognitive earning capacity and prevent catastrophic medical liabilities later in life. |
| Unavoidable Structural Inflation | Confusing exogenous cost hikes (childcare, property taxes, mandatory healthcare premiums) with hedonic status spending. | Separate voluntary status creep from involuntary survival overhead. Cut discretionary status leaks rather than blaming yourself for non-negotiable household inflation. |
Today’s 5-Minute Task: The Baseline Creep Audit
Take five minutes to verify whether your recent income growth converted into assets or permanent overhead:
- Pull Two Statements: Compare your total monthly checking and credit card outflows from 12 months ago against your most recent complete month (excluding investment transfers and one-off tax bills).
- Compute Monthly Creep Delta: Subtract last year’s baseline outflow from your current monthly outflow:
Creep Delta = Current Monthly Burn − Prior-Year Monthly Burn. - Calculate the 25× FIRE Penalty: Multiply any positive Creep Delta by
300(12 months × 25× rule). A silent $300/month spending creep adds $90,000 to your lifetime financial independence target. - Lock In the 80/20 Split: Create an automated recurring payday transfer routing 50%–80% of your latest raise (or planned next raise) directly into your investment or debt-payoff account before it sits in checking.
The Path Forward: True Wealth Is What You Don’t Spend
The measure of your financial power is never found in your gross W-2 statement, the badge on the hood of your automobile, or the square footage of an apartment you lease. Real wealth is the gap between your ego and your income. It is the unencumbered freedom to walk away from a toxic workplace, to weather an economic recession without panic, and to command your calendar without begging an employer for permission.
When you master the psychology of lifestyle inflation, every raise becomes permanent leverage toward your autonomy. You escape the frantic velocity of the hedonic treadmill, ground your life in deliberate simplicity, and build a fortress of genuine, lasting independence.
Leave a Reply